 Activix
 AutoTrader
 Black Book
 CarGurus
 Equifax
 TransUnion
Credit qualified leads
Know who can buy first
Credit qualified leads (CQLs) are shoppers who ran a soft credit check with your dealership before the first conversation. You see their credit profile, buying power and intent up front, with no impact on their credit score.
What are credit qualified leads?
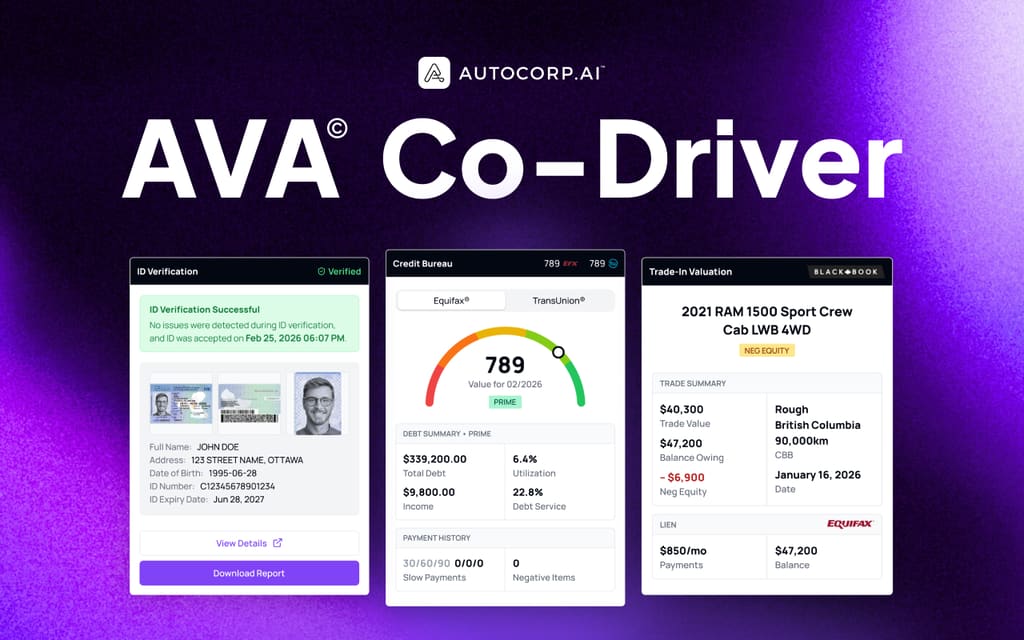
Credit qualified leads arrive with verified credit data attached. The shopper chose to check their own credit through a soft pull, so you get the same bureau data a lender would see, and they get a straight answer on what they can afford. Nobody has to ask the awkward questions on the first call.
Credit profile
Score, payment history, open trade lines and current obligations from a soft pull. No hard inquiry.
Buying power
What the shopper can realistically afford, based on their credit and existing debt.
Buyer type
Each lead is flagged as Prime, Subprime, Newcomer or Negative Equity so it reaches the right person.
Verified identity
Optional government ID and biometric checks confirm the shopper is who they say they are.
Internet leads vs. credit qualified leads
| Internet lead | Credit qualified lead | |
|---|---|---|
| What you get | Name, phone, email and a vehicle of interest | Contact details plus credit profile, buying power and buyer type |
| First conversation | Asking about budget, credit and down payment | Talking about vehicles and payments that fit |
| Intent | Unknown. The shopper could be browsing. | The shopper chose to check their credit, a strong buying signal |
| Routing | Round robin or first available rep | Prime to sales, subprime to finance, newcomers to the right programs |
| Credit impact | A hard pull later in the process | Soft pull only, with no effect on the shopper's score |
How AVA® creates credit qualified leads
-
Shopper starts a credit check
From your website, a QR code in the showroom, an SMS link or an ad, the shopper opens an AVA® credit form branded for your dealership.
-
Soft pull runs in seconds
AVA® pulls the credit report with a soft inquiry. The shopper sees their result right away and their score is untouched.
-
AVA® qualifies and routes
The lead is scored, tagged by buyer type and sent to the right person on your team.
-
Your team follows up with context
The CQL lands in your CRM and the AVA® portal, with the full credit picture ready before the first call.
Get credit qualified leads from every channel
Credit qualified leads, answered
What dealers ask when they first hear about CQLs.
What are credit qualified leads?
What does CQL stand for?
Does a soft pull affect the customer's credit score?
How are credit qualified leads different from pre-approvals?
Why do shoppers agree to a credit check?
Where do credit qualified leads show up for my team?
Start getting credit qualified leads
15 minutes. A working demo of the CQL flow, from the shopper's form to your CRM.